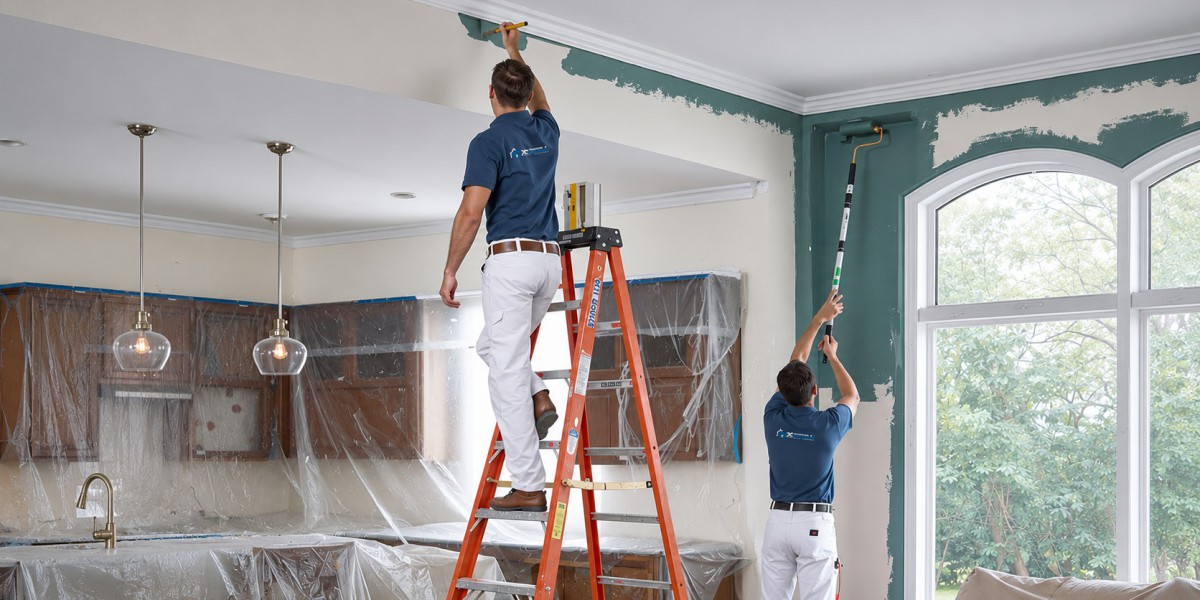

A fresh coat of paint can transform a home or business. It can also turn into an expensive headache if the wrong contractor holds the brush. Many property owners focus on price and color, then discover too late that their painter had no license, no insurance, and no obligation to fix anything that went wrong.
Quick Summary
- A license shows a painter meets legal and professional standards in your area.
- Insurance protects you from paying for accidents, injuries, and property damage.
- Hiring an unlicensed or uninsured painter can leave you personally responsible for costs that run into thousands of dollars.
- Verification takes about 15 minutes and is free in most cases.
What Does "Licensed" Actually Mean?
A license is official permission from a state, provincial, or local authority to operate as a painting contractor. Requirements differ widely by location. Some areas require a specific painting or specialty contractor license, while others only require a general business registration, and a few have no painting-specific rules at all.
Where licensing exists, it usually signals that the contractor has:
- Registered the business legally and can be traced if a dispute arises
- Met minimum experience, exam, or training requirements
- Agreed to follow local building, safety, and consumer protection rules
- Staked their professional standing on their work, since licenses can be suspended or revoked
Tip: Rules vary by region, so check with your local licensing board to learn what a painter is required to hold where you live.
What Does "Insured" Actually Mean?
Insurance is the financial safety net that pays for problems so you do not have to. A reputable painting company typically carries several types of coverage.
Type of Coverage | What It Protects | Why It Matters to You |
|---|---|---|
General liability insurance | Damage to your property or injury to third parties caused by the work | Covers things like paint spills on flooring, overspray on a neighbor's car, or a ladder crashing through a window |
Workers' compensation | Medical bills and lost wages if a painter is hurt on the job | Prevents you from being pulled into a claim if someone falls from a ladder at your home |
Commercial auto insurance | Vehicles used for business purposes | Protects against accidents involving company vehicles and equipment |
Surety bond (where offered) | Financial guarantee that the contractor will complete the job or follow licensing rules | Gives you a path to compensation if the contractor abandons the project |
A contractor who says "I'm covered" without showing proof is not covered as far as you are concerned. Always ask for documentation.
The Real Risks of Hiring an Unlicensed or Uninsured Painter
The lower quote from an unlicensed painter often looks like a bargain. It rarely stays that way. Here are the main risks.
1. You May Be Liable for Worker Injuries
Painting involves ladders, scaffolding, heights, and sometimes fumes or power equipment. If an uninsured worker is injured on your property, the medical bills and lost income claim can land on you. Depending on local law, your homeowner's policy may not cover it, especially if the injured person was a contractor rather than a guest.
2. You Could Pay for Property Damage Out of Pocket
Spilled paint, scorched trim from a heat gun, water damage from pressure washing, or a cracked window are all common mishaps. A insured company files a claim and the insurer pays. With an uninsured painter, you either chase them for payment or absorb the cost yourself.
3. Your Homeowner's Insurance May Push Back
Insurers can deny or dispute claims tied to work done by unlicensed contractors. If damage occurs and your insurer learns the work was not performed by a qualified, covered professional, you may face a denied claim or higher premiums.
4. Poor Workmanship With No Recourse
Without a license, there is usually no board to file a complaint with and no bond to claim against. If the paint peels in six months, the colors are wrong, or the job is left half finished, your options narrow to expensive legal action against someone who may be hard to find.
5. Safety and Environmental Violations
Older buildings may contain lead-based paint, and improper sanding or scraping can spread toxic dust through your home. In the United States, for example, federal rules require contractors working in most pre-1978 homes to be certified in lead-safe work practices. Many other countries have similar protections. Unqualified painters often skip these steps, putting your family, pets, and neighbors at risk and exposing you to fines.
6. Hidden Costs and Contract Problems
Unlicensed contractors are more likely to ask for large upfront payments, avoid written contracts, use cheaper materials than quoted, or disappear mid-project. Legal protections for homeowners often apply only when you hire a properly licensed contractor.
7. Problems When You Sell Your Property
Buyers and inspectors sometimes ask about the work done on a property. Poorly done or undocumented work can complicate a sale, lower your asking price, or trigger repair demands.
What a Real-Life Mistake Looks Like
Imagine you hire a painter for a two-story exterior job at a price 30 percent below other quotes. Midway through the project, a worker falls from a ladder and breaks his leg. The painter has no workers' compensation coverage. The injured worker files a claim that names you as the property owner. Your legal fees and the medical costs now far exceed the money you saved on the quote.
This scenario is not unusual, and it is entirely avoidable.
Benefits of Hiring a Licensed and Insured Painting Company
- Financial protection: Accidents and damage are handled by the contractor's insurer, not your wallet.
- Accountability: A licensed company has a reputation and a legal standing to protect.
- Higher quality work: Professionals are more likely to use proper prep methods, quality materials, and trained crews.
- Legal compliance: Permits, safety rules, and environmental standards are more likely to be followed.
- Warranty support: Established companies typically back their work with a written warranty they can actually honor.
- Peace of mind: You can focus on choosing colors instead of worrying about what might go wrong.
Step-by-Step Verification Guide
Do not rely on a website badge or a verbal promise. Follow these steps to confirm a painting company is the real thing.
Step 1: Ask for the License Number
A legitimate contractor will give you their license number without hesitation. Write it down exactly as provided, along with the full legal business name.
Step 2: Verify the License With the Issuing Authority
Look up the number on your state, provincial, or local licensing board website. Confirm that:
- The license is active, not expired, suspended, or revoked
- The name and address match the company you are dealing with
- The license covers painting or the type of work you need
- There are no serious complaints or disciplinary actions on record
Step 3: Request a Certificate of Insurance
Ask for a Certificate of Insurance, often called a COI. This document lists the insurer, policy numbers, coverage types, coverage limits, and effective dates. A professional company can usually email one within a day.
Step 4: Confirm Coverage Directly With the Insurer
A certificate can be outdated or even forged. Call the insurance company or the agent named on the certificate and confirm that the policy is currently active. Ask them to confirm the coverage limits as well.
Step 5: Ask to Be Named as a Certificate Holder
You can request that the insurer send you notice if the policy is canceled during your project. This is a common and reasonable request, especially for larger jobs.
Step 6: Check Workers' Compensation Status
In many places you can verify workers' compensation coverage through a government database. If the painter claims to work alone with no employees, ask for that in writing, and consider whether your area has different rules for sole proprietors.
Step 7: Review Reputation and History
License and insurance are essential, but they are not the whole picture. Also check:
- Online reviews on several platforms, not just one
- Better Business Bureau or similar consumer organization records
- Photos and addresses of past projects
- At least two or three recent customer references you can actually call
Step 8: Get Everything in Writing
A solid written contract should include:
- The full scope of work, including surface prep and number of coats
- Brand, type, and color of paint and primer
- Start and completion dates
- Total price and payment schedule
- Cleanup and disposal responsibilities
- Warranty terms
- License and insurance details
Red Flags to Watch For
Walk away, or at least slow down, if a painter:
- Refuses or delays showing a license or insurance certificate
- Pressures you to sign immediately with a "today only" discount
- Asks for a large cash payment upfront, such as more than 10 to 30 percent
- Offers a quote far below every other bid with no clear explanation
- Has no physical business address, website, or verifiable history
- Will not provide a written contract or warranty
- Offers to skip permits or lead-safe procedures to save money
- Cannot provide references
Questions to Ask Before You Hire
- Are you licensed in this area, and what is your license number?
- Can you send me a current certificate of insurance?
- Do you carry workers' compensation for every person on my job?
- Are your painters employees or subcontractors, and are subcontractors insured?
- What preparation work is included in this quote?
- What brands and grades of paint will you use?
- What does your warranty cover, and for how long?
- Who will be supervising the crew on site each day?
- How do you protect floors, furniture, and landscaping?
- What is your process if I am not satisfied with the result?
Licensed and Insured vs. Unlicensed and Uninsured: Side-by-Side
Factor | Licensed and Insured Company | Unlicensed or Uninsured Painter |
|---|---|---|
Upfront price | Often slightly higher | Often lower |
Injury liability | Covered by the contractor's policy | May fall on you |
Property damage | Insurer pays | You may pay |
Legal protections | Strong, with licensing board and bonds | Limited or none |
Warranty | Usually written and enforceable | Verbal or nonexistent |
Safety compliance | More likely to follow regulations | Often ignored |
Long-term cost | Predictable | Can be very high |
Frequently Asked Questions
Is a license the same as insurance?
No. A license shows legal authorization and qualification to do the work. Insurance protects you financially if something goes wrong. You need both.
Can't my homeowner's insurance cover everything?
Not reliably. Many homeowner's policies limit or exclude claims involving contractor injuries or work by unlicensed professionals. Never assume you are covered without checking with your insurer.
What if the painter says they are "between policies" or "about to renew"?
Do not start work until you see proof of active coverage. Past or future insurance does nothing for an accident that happens today.
Is it safe to hire a painter who works alone?
It can be, as long as they are properly licensed where required and carry general liability insurance. Verify whether workers' compensation is required for sole proprietors in your area, and ask for proof of the coverage they do hold.
How much more does a licensed and insured painter cost?
Quotes from fully compliant companies are often modestly higher because they pay for insurance, licensing, training, and proper materials. That difference is usually small compared to a single uncovered accident or a failed paint job.
Do I need to verify coverage for small interior jobs?
Yes. Even a single room involves ladders, chemicals, and the risk of damage to floors and furnishings. The risks are smaller, but they are still real.
Final Thoughts
Choosing a painter based only on the lowest price is one of the most common and costly mistakes property owners make. A licensed and insured painting contractors gives you accountability, legal protection, and confidence that the job will be done safely and correctly.
Before you sign a contract, take a few minutes to verify the license, request a certificate of insurance, confirm it with the insurer, and get everything in writing. That small investment of time can save you thousands of dollars and a great deal of stress.
A beautiful paint job should be the only surprise you get from your project.
Note: Licensing and insurance requirements differ by country, state, and city. Always confirm the specific rules that apply in your area with your local licensing authority.